A business valuation in a divorce is a professional appraisal that establishes what a company is worth so it can be counted and divided as part of the marital estate. In North Carolina, the value is set as of the date you and your spouse separated, and the appraiser reaches it using one or more standard methods, the asset, market, and income approaches. The incentives pull in opposite directions. The spouse who owns the business usually argues for a low number, and the spouse entitled to a share argues for a high one. That tension is why the value has to hold up to scrutiny.
At Rosen Law Firm, business owner and entrepreneur divorce is some of the work we do most, and we bring in CPAs and valuation experts to get the number right. We have practiced North Carolina family law for more than 30 years, and about 85% of our cases settle through mediation, where a solid valuation often carries the whole conversation. This guide covers what a business valuation is, when you actually need one, how North Carolina rules shape the value, and what happens once the number is set.
What is a business valuation in a divorce?
A business valuation is an independent appraisal of what a company is worth, prepared so a business owned by one or both spouses can be counted and divided with the rest of the marital property. Its job is to pin down each spouse’s marital interest in the business, which then feeds into how everything else gets divided.
The work runs parallel to what a real estate appraiser does with a house. A home appraiser walks the property and studies comparable sales to land on a value. A business appraiser digs into the financials and the way the company actually runs, then applies recognized methods to reach a number that will hold up. The result is a written report you, your spouse, and a judge can all work from.
Do you need a business valuation in your divorce?
Not every divorce that involves a business needs a formal valuation. It makes sense when the business is a significant marital asset and the two of you do not agree on what it is worth. It is often unnecessary when the business has little value or you already see eye to eye on how to handle it.
You will usually want a valuation when:
- The business is one of the larger assets in the marriage.
- You and your spouse disagree about what it is worth.
- One spouse controls the finances and the other cannot see the full picture.
- The business will be bought out, sold, or divided as part of the settlement.
You may be able to skip a formal appraisal when the business is worth very little, when it has no real value apart from the owner’s own labor, or when you both already agree on a number and how to split it.
The businesses that most often get valued are the ones with real money behind them: medical, dental, and dermatology practices, technology start-ups, accounting firms, construction companies, and large farming operations. Paying to value a small lawn-care business or an in-home daycare is rare. Some fields carry their own complications, and if a professional practice is in the mix, our guide on valuing a medical practice during divorce goes deeper.
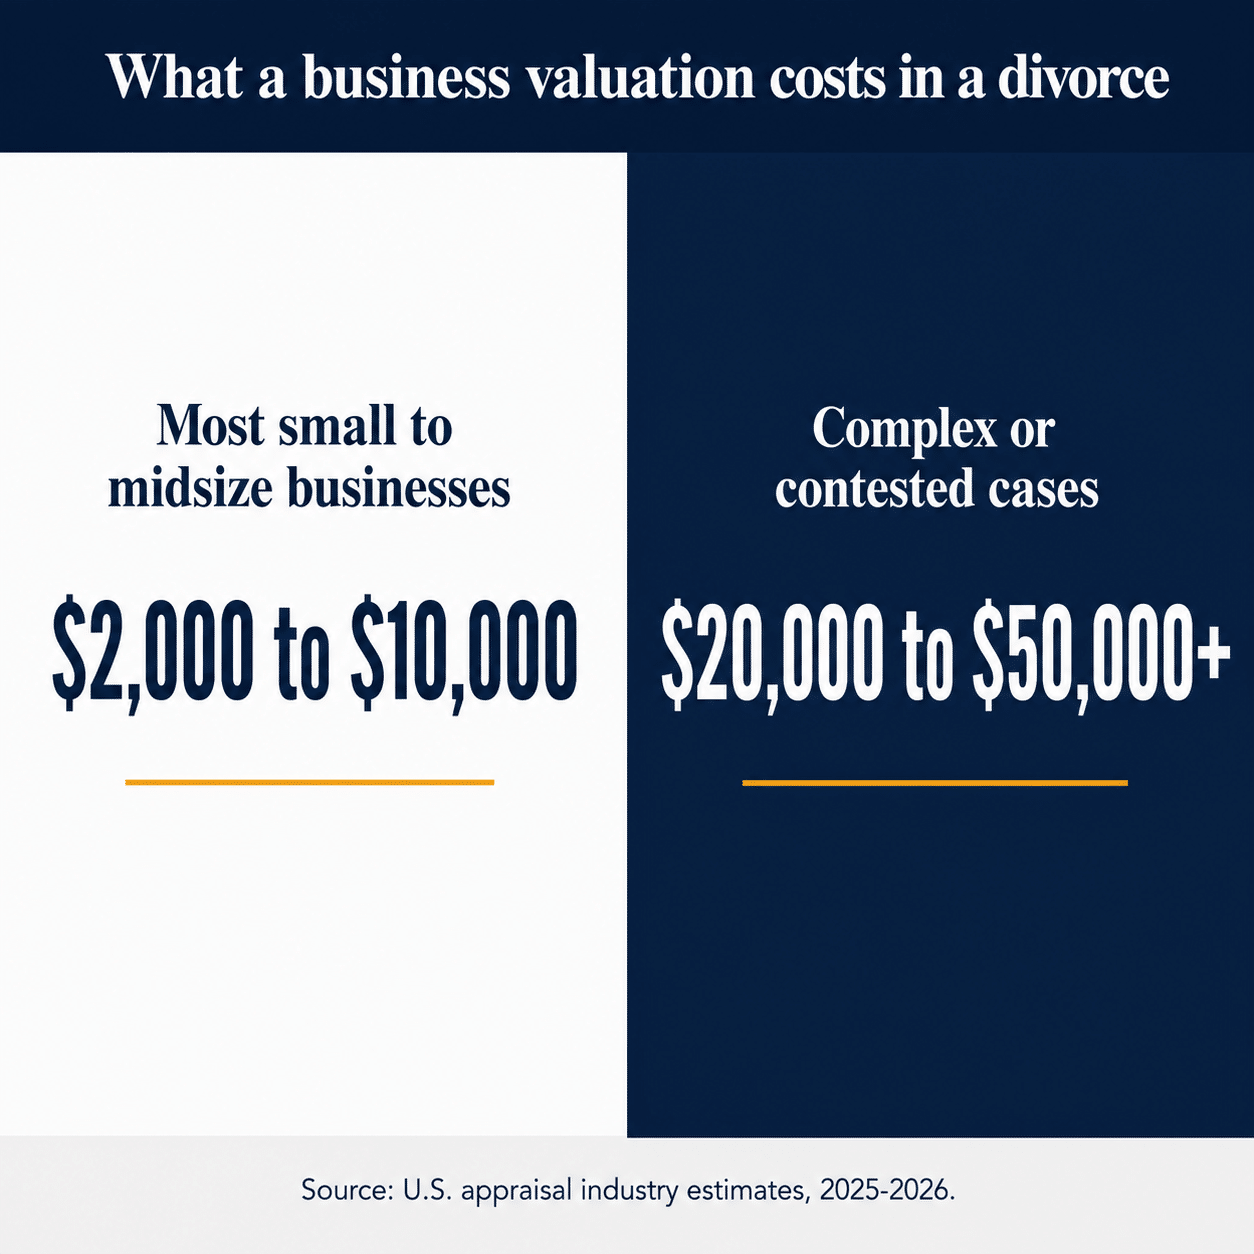
Cost is a fair thing to ask about up front. For most small and midsize businesses, a valuation runs about $2,000 to $10,000. A comprehensive report built for a contested case can reach $20,000 to $50,000 or more, depending on the size and complexity of the business, the methods used, and whether it is headed to court.
When is a business valued in a North Carolina divorce?
In North Carolina, marital property is valued as of the date of separation. The statute that governs the procedure, N.C.G.S. 50-21, says marital property is valued as of the day the parties separated, so the appraiser sets the business’s fair market value on that date, not on the day of trial or settlement.
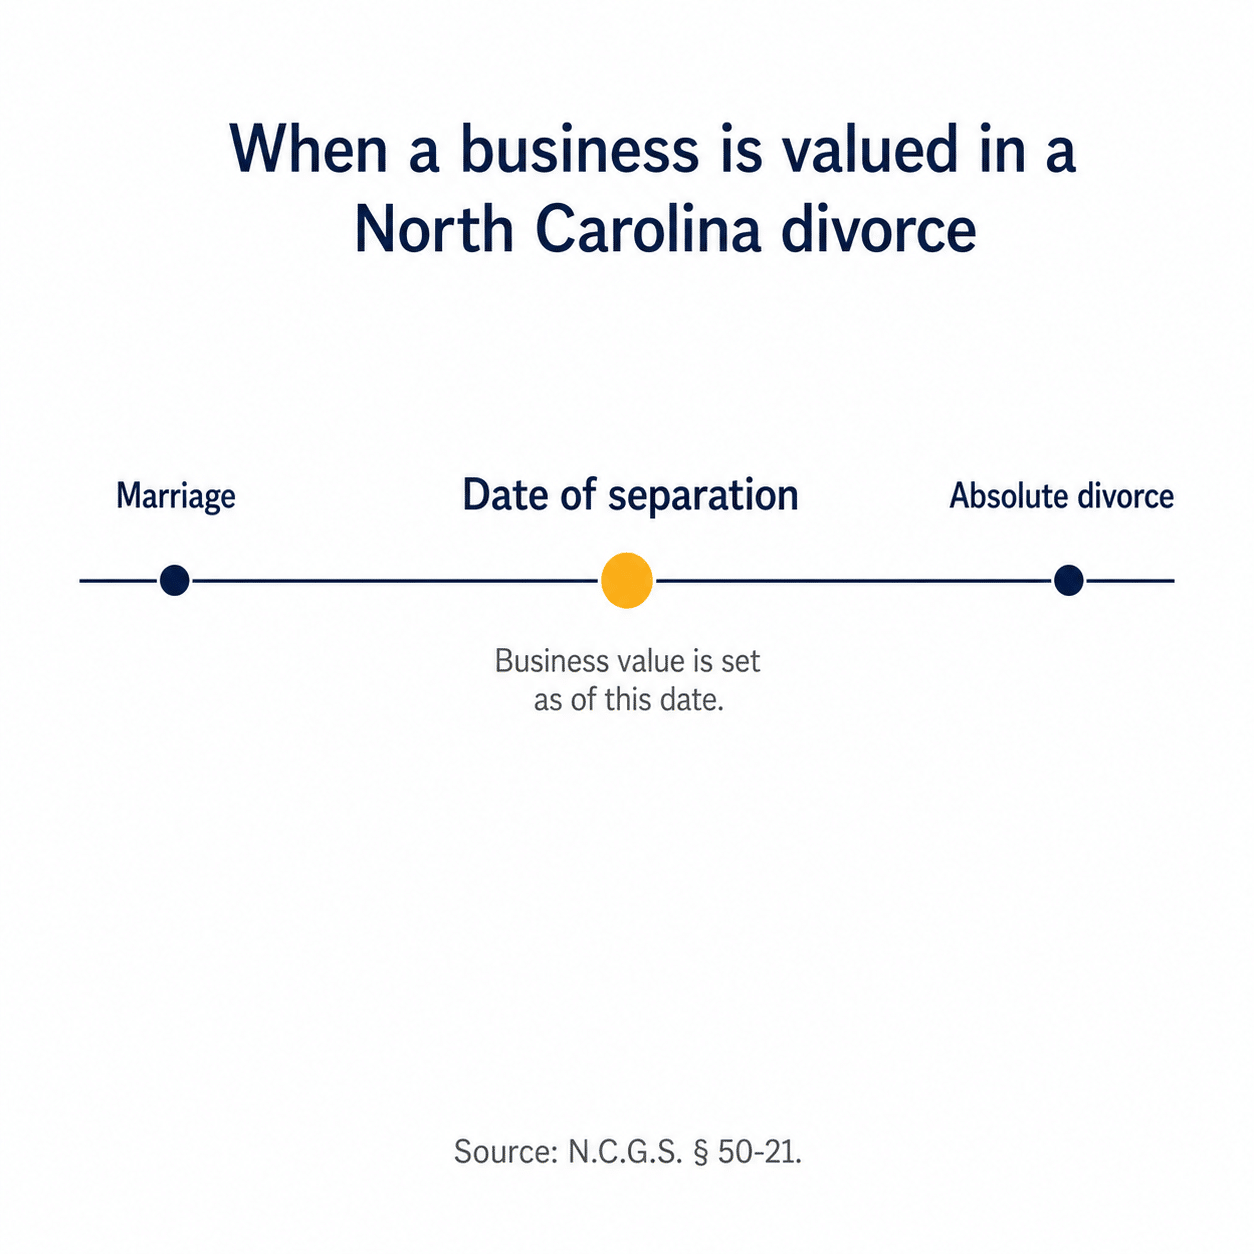
That single rule has real consequences. A business can change a lot between separation and a final division, and that gap often runs many months or longer. Changes in value after separation are usually treated as divisible property and handled at distribution. There is one important exception: if the business grows after separation because of one spouse’s own work, that growth generally is not shared with the other spouse. If you are worried a business will take off once the case is over, our article on whether a spouse can benefit when a business grows after settling walks through how that plays out.
Is your business marital or separate property?
Before any value gets divided, the business has to be classified. In North Carolina, a business interest can be marital, separate, or divisible property, and that label decides how much of the value is actually on the table.
Property acquired during the marriage and owned at separation is presumed marital. Property one spouse owned before the marriage, or received as a gift or inheritance, is generally separate. So a business launched during the marriage is usually marital from day one, while a business one spouse founded beforehand starts out as that spouse’s separate property.
Growth is where it gets complicated. North Carolina courts split appreciation into two kinds:
- Active appreciation is growth that comes from a spouse’s effort or from marital money during the marriage. When a separate business grows for those reasons, the increase is treated as marital property.
- Passive appreciation is growth from outside forces like inflation or the market, with no marital effort behind it. That increase generally stays separate.
So a business one spouse owned before the wedding is not automatically off-limits. If the couple’s work or money helped it grow during the marriage, that growth can be marital and open to division. Figuring out how much of a company’s value came from marital effort is one of the harder parts of a valuation, and a common flashpoint between the spouses.
How goodwill affects your business’s value
Goodwill is the intangible value of a business beyond its physical assets, the reputation, client relationships, and earning power that make it worth more than its equipment and inventory. Appraisers often sort goodwill into two buckets. Enterprise goodwill belongs to the business itself and would carry over to a new owner. Personal goodwill is tied to the individual owner’s skill, reputation, and relationships.
Some states leave personal goodwill out of the marital estate. North Carolina does not. Our courts fold business goodwill into the value that gets divided, and they have consistently declined to separate personal from enterprise goodwill. A 2024 North Carolina Court of Appeals decision, Sneed v. Johnston, reaffirmed that calling goodwill “personal” does not keep it out of the marital estate.
For a business owner, that is worth knowing going in. In North Carolina, the value of your reputation and client base can count toward what the business is worth in the divorce, even though it never shows up on the balance sheet.
The three approaches appraisers use to value a business
Business appraisers work from three standard approaches. Most reports use more than one and explain why a particular method carried the most weight.
| Approach | How it works | Best suited for | Main limitation |
|---|---|---|---|
| Asset approach | Adds up the business’s assets at fair market value and subtracts its liabilities | Holding companies and asset-heavy or low-earning businesses | Often misses goodwill and other intangible value |
| Market approach | Compares the business to similar companies that have sold and applies valuation multiples | Businesses with good comparable sales data | Truly comparable sales are often hard to find |
| Income approach | Projects future earnings or cash flow and discounts them to present value at a risk-adjusted rate | Operating businesses with steady earning power | Small changes in assumptions can swing the value widely |
For an operating business, the income approach usually carries the most weight, because it captures the company’s ability to generate future earnings, which is where much of the value sits. The market approach comes in when solid comparable sales exist. The asset approach often works as a floor or a cross-check on the other two. A company with heavy hard assets, like real estate or large inventory, may lean on the asset method for that part of its value.
Two honest appraisals can still reach different numbers, and this is usually where it happens. The methods depend on judgment about which earnings count as normal, what discount rate reflects the real risk, and whether a comparable sale is truly comparable. Knowing where those judgment calls live helps you read a valuation with a sharper eye.
What standard of value applies?
North Carolina equitable distribution uses fair market value, the price a business would sell for between a willing buyer and a willing seller, with neither under pressure to act. In practice, appraisers in divorce cases lean on the framework in IRS Revenue Ruling 59-60, the long-standing standard for valuing closely held businesses at fair market value. Rather than plug numbers into one formula, it asks the appraiser to weigh factors like the company’s history, its industry and economic outlook, book value, earning capacity, dividend-paying capacity, and goodwill. Our overview of what Revenue Ruling 59-60 means for a business valuation breaks the factors down.
What the appraiser needs from you
Choosing the appraiser is the first real step, and it pays to be picky. Look for a business valuation professional, often a CPA or a credentialed appraiser, who has valued your type of business and prepared reports for court. Common credentials include:
- ASA, Accredited Senior Appraiser (American Society of Appraisers)
- CVA, Certified Valuation Analyst (NACVA)
- ABV, Accredited in Business Valuation (AICPA)
- CFA, Chartered Financial Analyst
Credentials are only part of it. Ask how many valuations the appraiser has done and how often they have testified in a divorce. If your case goes to court, you want someone who can explain and defend their work on the stand. Judges tend to lean hard on a well-built valuation, since it is usually the most reliable evidence of value beyond what the spouses themselves say.
Then come the documents, and most of them sit with the spouse who runs the business. North Carolina’s process helps here. Each spouse files an equitable distribution inventory affidavit listing assets and their fair market values as of separation, and broad discovery lets you request records from the other side. An appraiser generally needs:
- Business and personal tax returns, usually the last three to five years
- Financial statements, including income statements and balance sheets
- General ledgers and bank statements
- Contracts, customer lists, and evidence of upcoming work
- Any prior valuations or buy-sell agreements
- Records specific to the industry
With those in hand, the appraiser builds a full financial picture, and may interview management or visit the business before settling on a value.
What the business valuation report looks like
The valuation itself is a written report, usually several pages, and it follows a predictable shape. A table of contents lays out how it is organized. The opening summary gives the appraiser’s conclusion, the value assigned to the business. From there, the report walks through each method used, why it was chosen, and the analysis behind the final number, and it lists every source the appraiser relied on. That structure is what makes a valuation persuasive. A reader can trace exactly how the appraiser got from the financials to the value.
How the valuation is used to divide the business
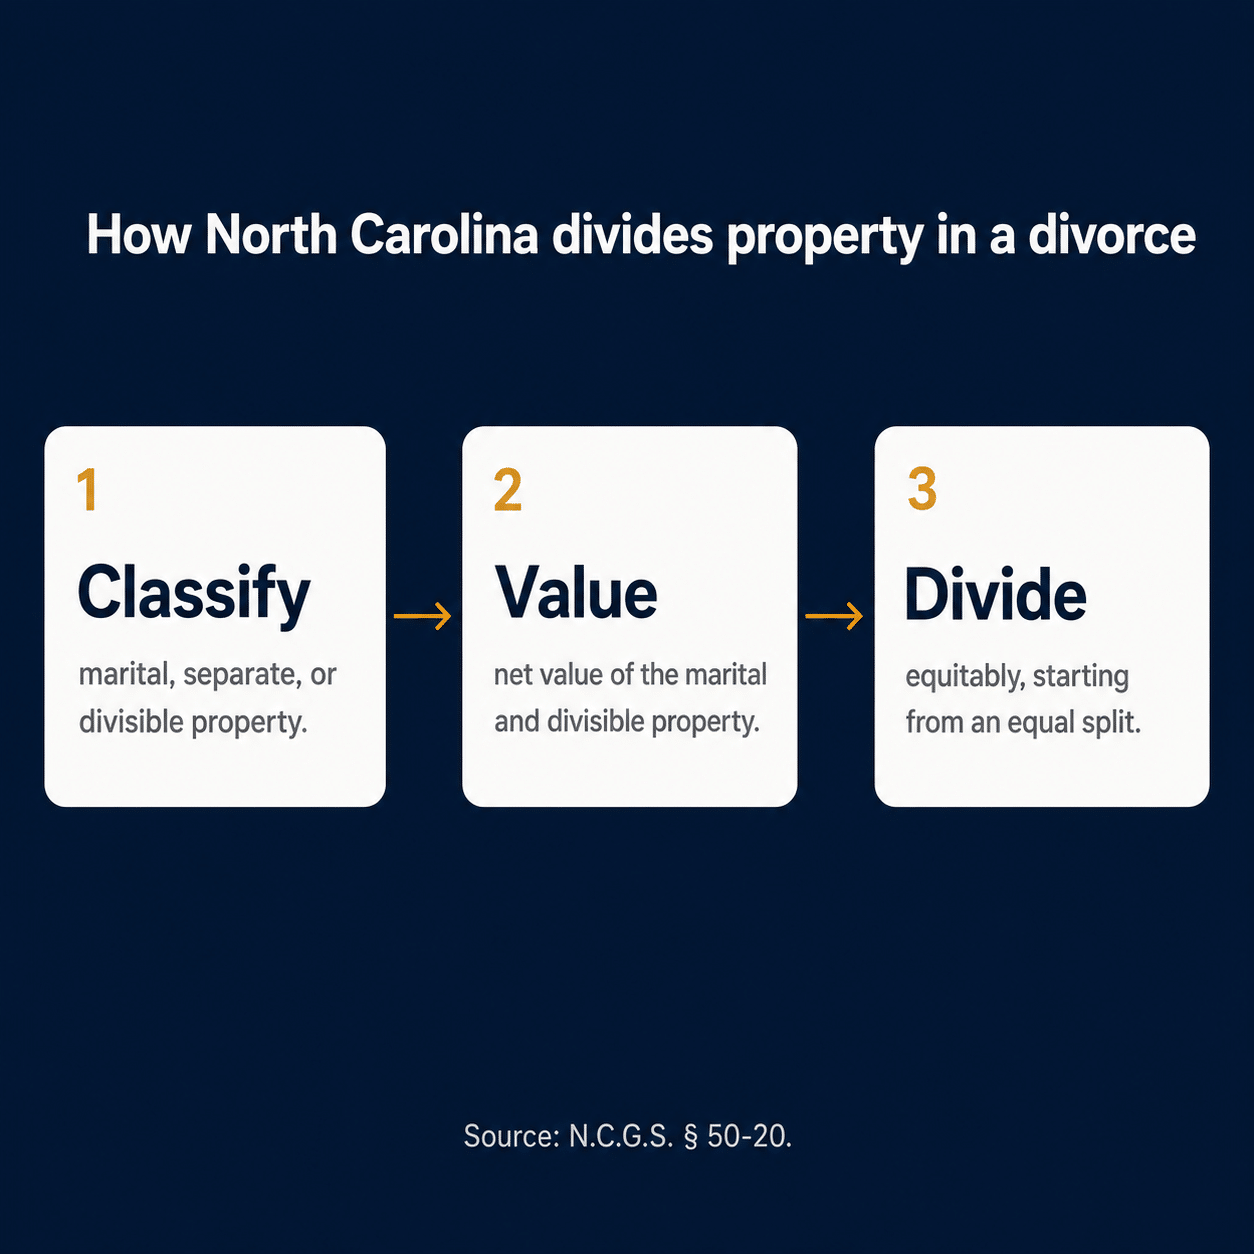
Once the value is set, it becomes the key input for dividing the marital estate under North Carolina’s equitable distribution law, N.C.G.S. 50-20. The process runs in three steps. The court classifies the property, determines the net value of the marital and divisible property, and then divides it. North Carolina starts from a presumption that marital property is split equally, unless the court decides an equal split would be unfair after weighing a list of statutory factors. One of those factors is the difficulty of valuing a business and the value of keeping it in one piece, which our overview of equitable distribution in North Carolina covers in more detail.
North Carolina County Courthouse Information
| County | Address | Hours |
|---|---|---|
| Wake County | 316 Fayetteville St Raleigh NC 27601 | Monday: 8:30am-5:00pm Tuesday: 8:30am-5:00pm Wednesday: 8:30am-5:00pm Thursday: 8:30am-5:00pm Friday: 8:30am-5:00pm Saturday: Closed Sunday: Closed |
| Durham County | 510 S Dillard St Durham, NC 27701 | Monday: 8:30am-5:00pm Tuesday: 8:30am-5:00pm Wednesday: 8:30am-5:00pm Thursday: 8:30am-5:00pm Friday: 8:30am-5:00pm Saturday: Closed Sunday: Closed |
| Chatham County | 40 E Chatham St Pittsboro, NC 27312 | Monday: 8:30am-5:00pm Tuesday: 8:30am-5:00pm Wednesday: 8:30am-5:00pm Thursday: 8:30am-5:00pm Friday: 8:30am-5:00pm Saturday: Closed Sunday: Closed |
| Johnston County | 207 E Johnston St #209 Smithfield, NC 27577 | Monday: 8:00am-5:00pm Tuesday: 8:00am-5:00pm Wednesday: 8:00am-5:00pm Thursday: 8:00am-5:00pm Friday: 8:00am-5:00pm Saturday: Closed Sunday: Closed |
| Orange County | 106 E Margaret Ln Hillsborough, NC 27278 | Monday: 8:30am-5:00pm Tuesday: 8:30am-5:00pm Wednesday: 8:30am-5:00pm Thursday: 8:30am-5:00pm Friday: 8:30am-5:00pm Saturday: Closed Sunday: Closed |
That preference for keeping a business whole shapes your real options once you have a number. There are three:
| Option | How it works | When it fits |
|---|---|---|
| Buyout | One spouse pays the other for their share and keeps the business | One spouse wants to keep running the business and can fund the payment |
| Sale | The business is sold and the net proceeds are divided | Neither spouse wants to keep it, or a buyout is not workable |
| Continued co-ownership | Both spouses remain owners after the divorce | Rare, and only when both can keep working together |
Our guide on dividing a business in a divorce walks through how to choose among these paths.
Where the case is resolved changes how the valuation is used. In mediation, the written report is usually enough on its own, since the process is less formal and the strict rules of evidence do not apply. In court, the appraiser generally has to appear and testify about how they reached the value and why they are qualified. Sometimes spouses agree to share one appraiser. Sometimes each hires their own.
When two appraisers disagree, North Carolina judges do not simply split the difference. A judge weighs the evidence and adopts a value supported by the record, which may be one expert’s figure or a number somewhere in the range of the testimony. That is why the credibility of the valuation, and of the appraiser behind it, counts for more than chasing an aggressive number.
What to do if you think the value is wrong
If you suspect the business is worth more than the other side claims, you have real tools, and you should use them. The value rests on the underlying financials, so full disclosure is your first line of defense.
- Use discovery fully. You are entitled to the business’s records. A careful read of tax returns, ledgers, and bank statements often turns up income or assets that a summary leaves out.
- Bring in a forensic accountant. When you suspect income is being hidden or pushed off, a forensic accountant can trace cash flows, reconstruct unreported income, and catch tactics like delaying billing until after the divorce. Our article on finding hidden assets during divorce covers the usual ones.
- Get a second opinion. If an appraisal looks off, another appraiser can pick apart its assumptions, its treatment of earnings, and its discount rate. Watch for inflated expenses, related-party transactions, and growth forecasts that do not match reality.
The same tools protect a business owner who thinks the other side’s appraiser has overstated the value. A credible valuation and a clear-eyed look at the numbers cut both ways.
Frequently asked questions
How much does a business valuation cost in a divorce?
Most valuations of small and midsize businesses cost between $2,000 and $10,000. A comprehensive report prepared for a contested case can run $20,000 to $50,000 or more, depending on the size and complexity of the business.
Is a business I started before marriage protected in a divorce?
The value your business had before the marriage generally stays your separate property. But if the business grew during the marriage because of marital effort or funds, that growth can be treated as marital property and divided. Passive growth from market forces usually stays separate.
Can my spouse lower the business’s value by hiding income?
It happens, which is why discovery and, in some cases, a forensic accountant matter. Deferring revenue, running personal expenses through the business, and skimming cash are recognized tactics that a careful financial review is built to catch.
Does North Carolina treat personal goodwill separately?
No. North Carolina includes both personal and enterprise goodwill in the value of a business for equitable distribution, and its courts have declined to draw a line between the two.
Talk to us about your business valuation
If a business is part of your divorce, the value is worth getting right, and you do not have to sort it out alone. At Rosen Law Firm, we handle business owner and entrepreneur divorce across the Triangle, and we set a fixed fee up front so you know your cost from the start, with no hourly billing and no surprises. We work with CPAs and valuation experts, and we push to settle through negotiation and mediation whenever we can, so the valuation becomes a tool for a fair result instead of ammunition for a fight.
Learn more about how we handle business owner and entrepreneur divorce in North Carolina, or take the next step and set up a consultation. You can also call or text us at (919) 787-6668.
Lisa is a leading figure in North Carolina’s family law field, dedicated to guiding clients through challenging times with compassion and expertise. As the President and Owner of Rosen Law Firm, P.A., Lisa has built a successful practice specializing in divorce, child custody, child support, alimony, equitable distribution, and domestic violence. She has been a North Carolina Board-Certified Specialist in Family Law since 1998.